

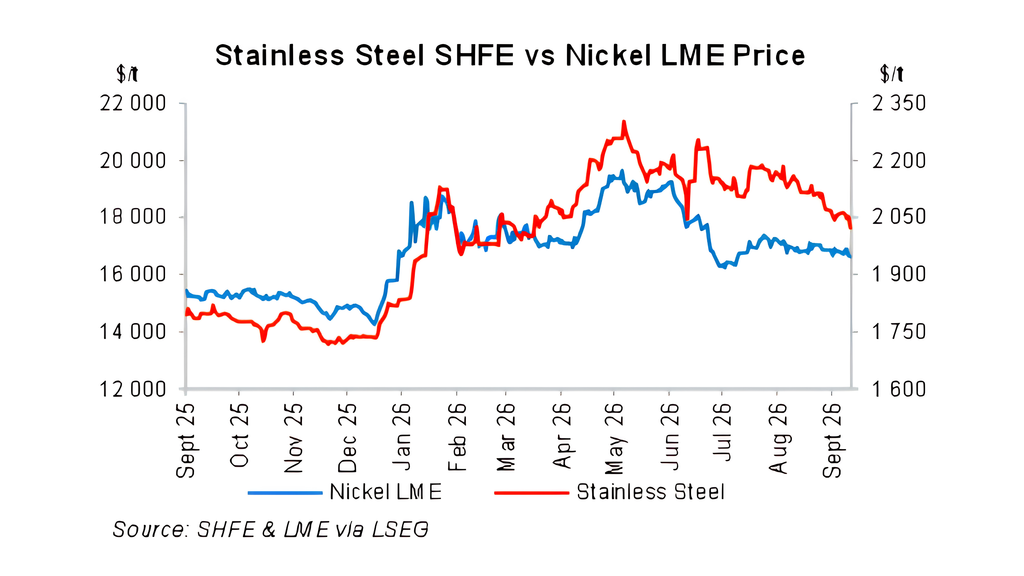
Stainless steel prices continue their downwards trend that started around the middle of the year due to ongoing weakness in Chinese domestic demand; nickel prices, though, remain above their 2025 lows, providing some cost support to stainless steel prices (see graph).
Global stainless steel demand remains subdued as China – which accounted for 58% of global consumption in 2025 – continues to face weak manufacturing activity, a property sector in crisis and slow domestic consumption. The anticipated “Golden September” restocking ahead of the traditional September-October peak construction season has so far failed to materialise.
The decline in some stainless steel inventories has also not necessarily represented stronger end-user consumption, with part of the reduction linked to warrant outflows rather than genuine demand improvement.
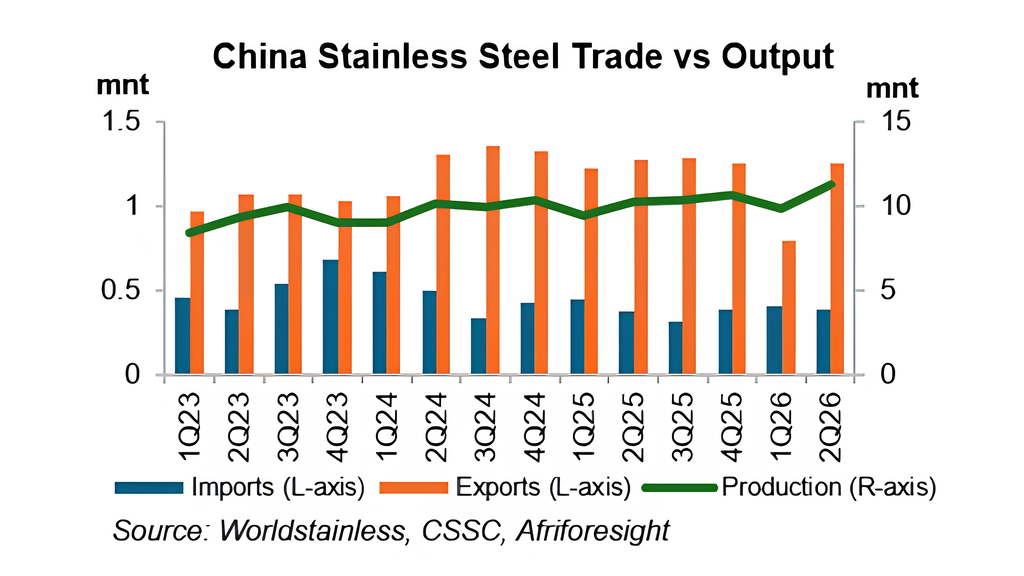
The weakness in Chinese domestic demand is putting increasing pressure on stainless steel mills. Producers continue to face weak margins and have been focusing on cost control, with some reducing production schedules and pausing raw-material procurement as existing inventories remain sufficient. Despite these pressures, China’s stainless steel production has remained elevated as output strengthened significantly during the 1st half of 2026; even though exports remained below levels seen in the previous year, they did recover somewhat in the 2nd quarter, but not enough to fully offset weak domestic demand, leaving the market relatively well supplied – see graph below.
Grade 304 stainless steel (the benchmark grade) contains a relatively high nickel content and fluctuations in stainless steel prices typically closely mirror movements in nickel prices. While nickel prices continue to provide some support to stainless steel markets, the broader fundamentals remain weak – recent strength in nickel prices is partly reflective of uncertainty regarding ore production in Indonesia (the world’s largest producer), rather than a clear improvement in underlying nickel demand for stainless steel production.
The key question is whether Chinese demand will improve ahead of the National Day holiday in October. So far, the expected peak-season recovery has not emerged, and if pre-holiday restocking remains limited, stainless steel prices are likely to remain under pressure despite occasional support from nickel prices and export market.
For more on the outlook for Stainless steel & Nickel; see our Stainless steel & Nickel forecasts.
Compiler: Khomotso Rabutla (khomotso@afriforesight.com)