

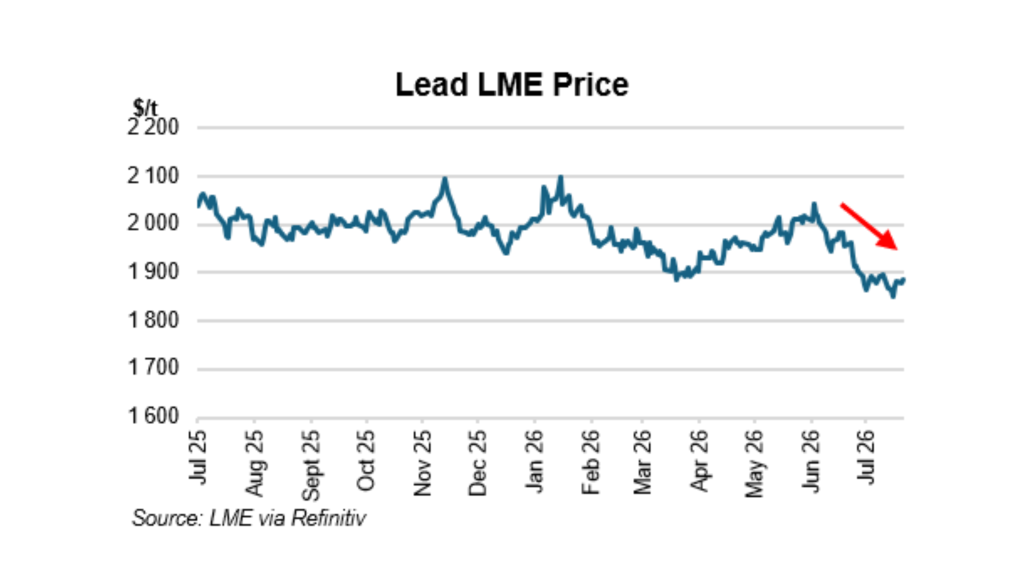
Lead ore prices remain under pressure as LME (refined) lead prices fell to 15-month lows, weighed down by a sharp increase in exchange inventories and subdued downstream demand in China – see graph below.
A record influx of lead into LME warehouses, linked to deliveries by Trafigura and continued inflows from Indian refiners, has pushed visible stocks to their highest level since 2012 – see graph below. Much of this metal is understood to have originated from India’s rapidly expanding refining sector, where higher production and export availability have created surplus supply that has increasingly been channelled into the LME warehouse system.
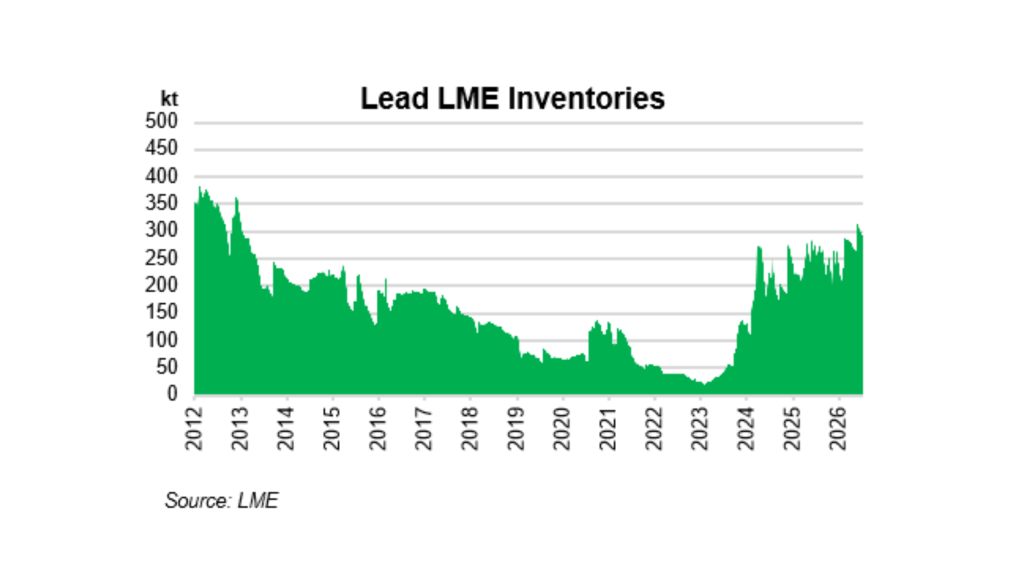
As inventories mount, market fundamentals remain weak, with rising secondary lead production continuing to outpace demand growth. In China, soft replacement demand for lead-acid batteries and slower activity across the battery manufacturing sector have further limited consumption, contributing to persistent price weakness.
Looking ahead, lead prices are expected to remain under pressure unless visible inventories decline meaningfully or demand from China’s battery sector improves. While increased Chinese imports of Indian refined lead could gradually divert some material away from LME warehouses, the current stock overhang is likely to keep the market well supplied in the near term.
For more on the outlook for Lead; see our Lead forecasts.
Compiler: Khomotso Rabutla (khomotso@afriforesight.com)