

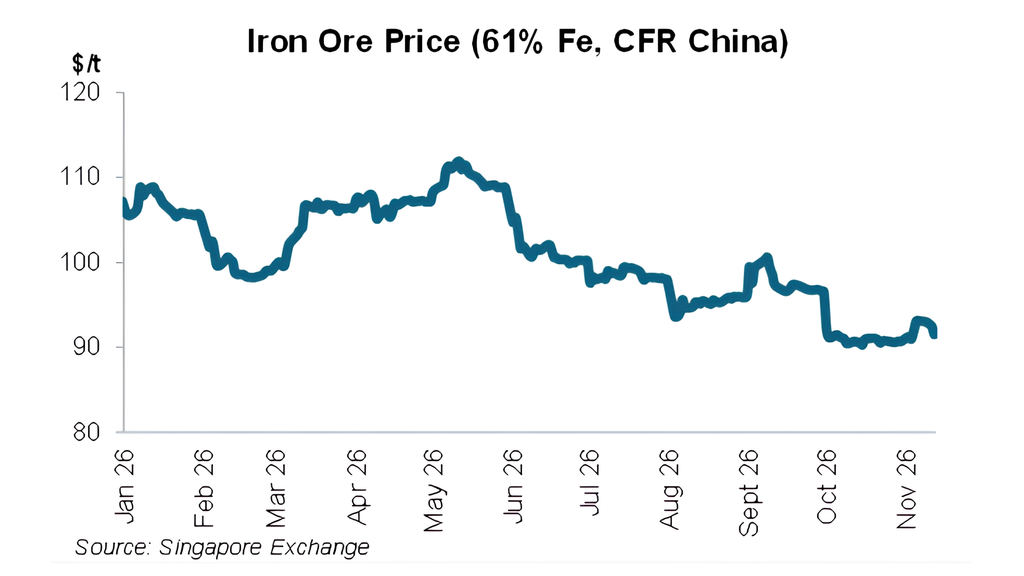
Global iron ore prices are facing renewed downward pressure as supply increases while demand from China continues to weaken. The latest expansion at Guinea’s Simandou project comes as Chinese steelmaking slows and winter pollution restrictions threaten to reduce production further, raising concerns about growing oversupply.
On 6 November, China’s Baowu Steel Group commissioned the 2nd 30mntpa production line at Simandou’s northern mining blocks after completing its mine-to-port logistics chain, bringing the operation’s combined planned capacity to 60mntpa. Its 1st line, commissioned in November 2025, has already produced and shipped more than 10mnt of iron ore. Meanwhile, the southern SimFer operation has also begun exporting ore and is expected to gradually increase production to 60mntpa during the 2nd half of 2028. Together, the operations are designed to eventually produce around 120mntpa of high-grade iron ore, significantly increasing competition in the global market.
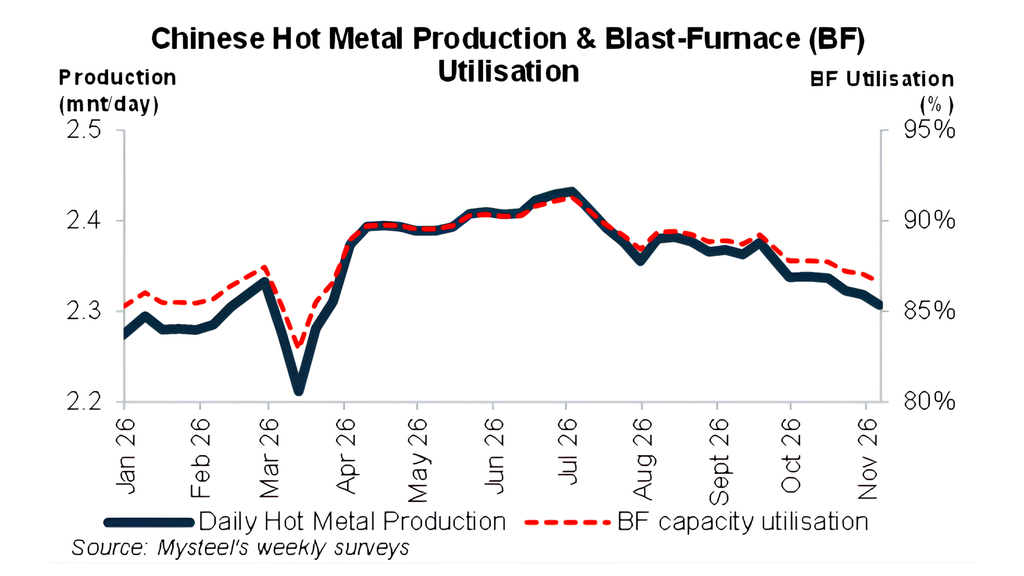
Meanwhile, Chinese steelmaking volumes have declined since July amid weak steel demand and pressure on mill profitability. Both hot metal production and blast furnace capacity utilisation have declined, while major steelmaking centres, including Tangshan and Handan, introduced pollution restrictions in November. Although these measures have mainly affected sintering operations so far, further restrictions could reduce iron ore consumption in the coming months.
For South African exporters, growing competition from Simandou could put additional pressure on iron ore prices and profit margins. While high-quality South African ore remains attractive to international buyers, the impact will depend on how quickly Simandou increases shipments and whether other steelmaking markets can absorb the additional supply.
With Chinese steelmaking slowing and more iron ore entering the market, prices could struggle to recover over the rest of the year. Seasonal restocking and the loss of some lower-cost production should put a floor under the price for now, but without stronger demand from Chinese steelmakers, any recovery is likely to be short-lived.
For more on the outlook for Iron Ore; see our Iron Ore forecasts.
Compiler: Devon Allers (devon@afriforesight.com)