

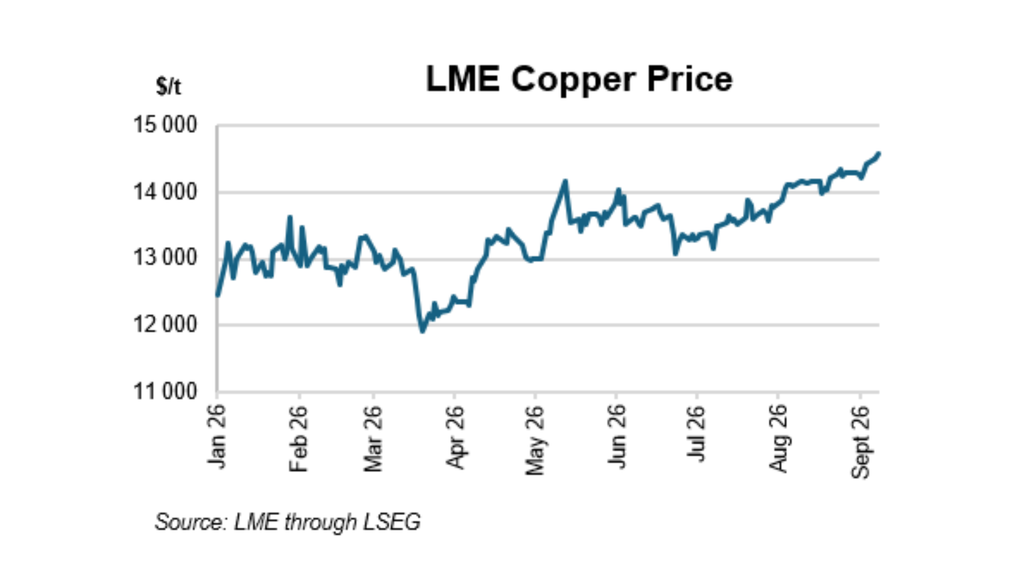
Copper prices surged to a fresh record high of above $14 500/t (see graph), driven by mounting concerns over tight supply outside the US, with a weaker dollar also contributing upwards pressure. Uncertainty over potential US tariffs on refined imports continues to distort trade flows, drawing large volumes into COMEX warehouses, which are now at record levels, while inventories elsewhere remain depleted. While the market is focussed on these movements in refined supply, more broadly, weather disruptions combined with ageing mines, declining ore grades and project delays, are weighing on the global production outlook for 2026.
The core issue limiting supply remains mined output setbacks. Freeport-McMoran’s Grasberg mine in Indonesia is still recovering from a September 2025 landslide, while the Ivanhoe/Zijin Mining’s Kamoa-Kakula mine in the DRC is still operating below capacity after flooding in May last year. Global mined production slipped in the first half of 2026, with Codelco, Freeport, and other majors reporting steep declines. Following years of under-investment in new projects, there is limited new supply available to offset these disruptions.
Weather risks are increasingly adding another layer of uncertainty to future copper supply. Extreme weather has severely disrupted operations in Chile: Antofagasta’s first half output was 15.9% lower than in the second half of 2025; operations were also halted at Los Pelambres mine in July, prompting Antofagasta to cut its 2026 production guidance to 625-655kt, 5.2% below its previous forecast. Forecasts of a strengthening El Niño raise the risk of further interruptions. Chile is particularly exposed, while hydropower-dependent mines in the DRC and Zambia are also vulnerable to rising temperatures.
With copper prices already approaching $15 000/t, the market is becoming increasingly sensitive to further supply shocks. The combination of ageing mines, weather-related disruptions and a thin project pipeline points to a structurally constrained and increasingly volatile copper market, with limited relief from new supply in the near term.
For more on the outlook for Copper; see our Copper forecasts.
Compiler: Dina Alleluya (dina@afriforesight.com)