

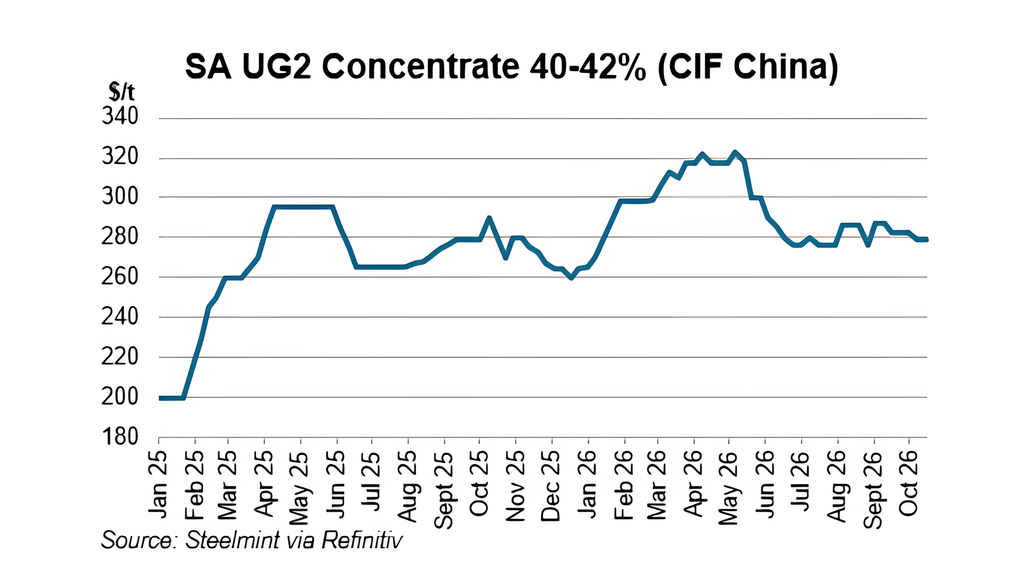
Chrome ore prices extended their decline as supply growth continues to outpace Chinese demand: expectations of a seasonal recovery during “Golden September and Silver October” failed to materialise, and although inventories began to decline in October, a reduction in shipments has yet to translate into a meaningful price recovery as buyers remain cautious.
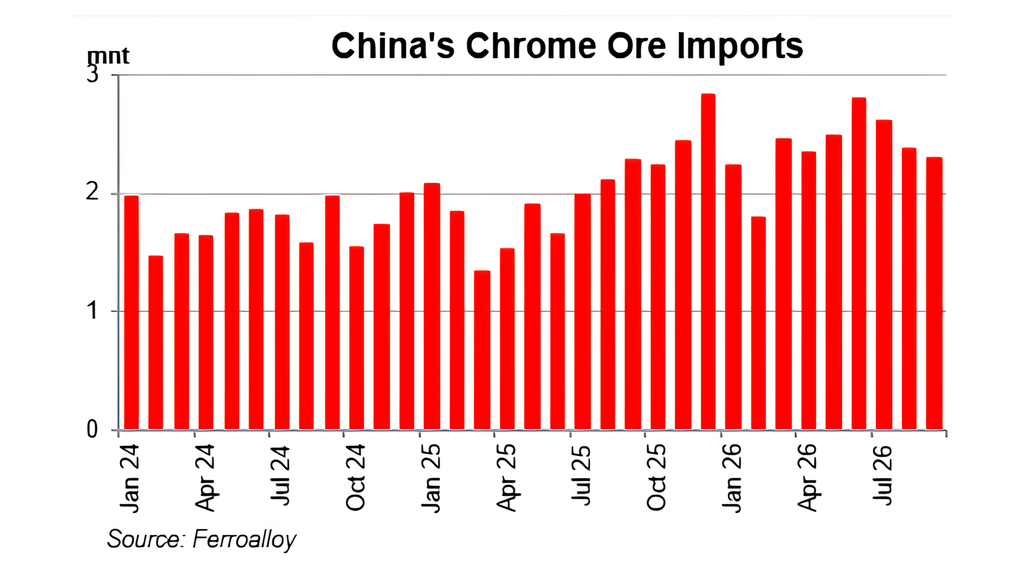
China’s chrome ore imports were down 4.6% in 3rd quarter 2026 from the 2nd quarter – see graph below. South Africa remained China’s dominant supplier with around 80% of imports. Despite the moderation in shipments – tied to increased fuel costs amid the Middle East war – continued output from African producers kept the market well supplied.
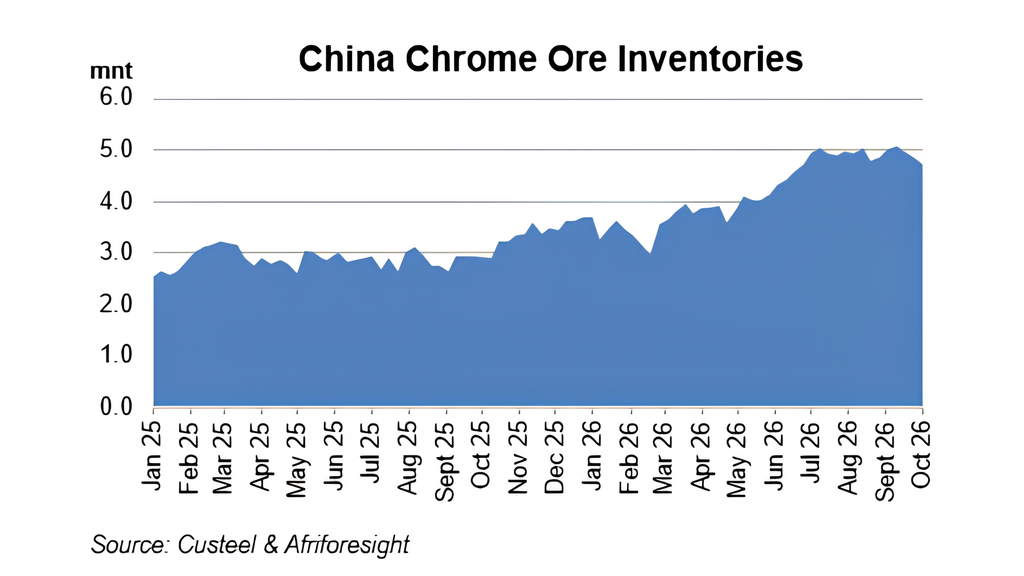
However, lower imports did little to ease the supply overhang in China. Chinese port inventories remained elevated at around 5mnt, still up about 28% above the beginning of 2026 level – see graph below, limiting buyers’ urgency to replenish stocks.
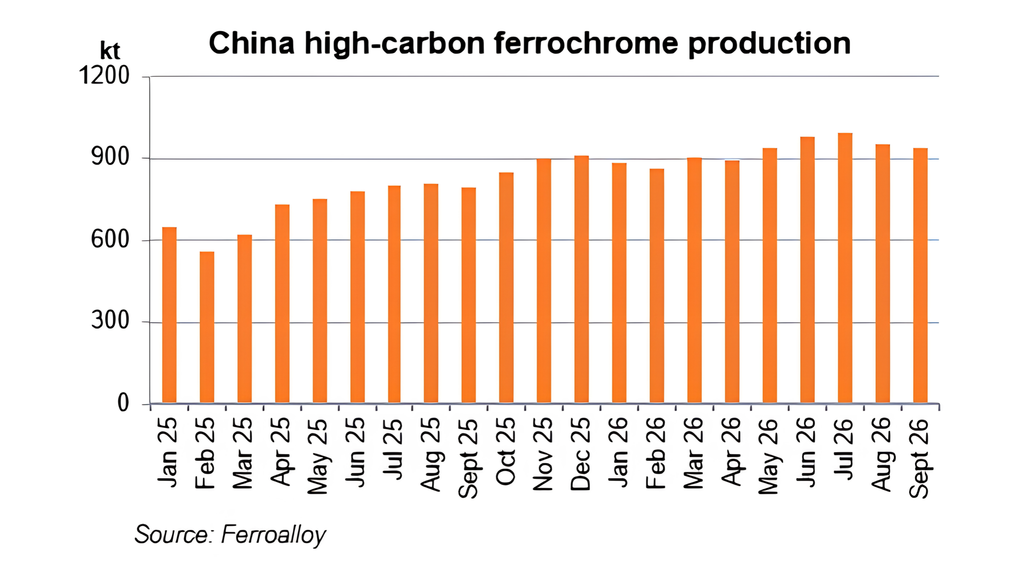
Meanwhile, the anticipated seasonal demand recovery failed to provide the boost needed to reverse the market’s downward trajectory. Weaker stainless steel demand weighed on China’s ferrochrome sector, with production easing from July – see graph below. Although high-carbon ferrochrome output remained above year-earlier levels, surplus concerns limited smelters’ appetite for additional chrome ore.
With supply remaining resilient and Chinese buyers still well stocked, the market’s recovery hinges on a meaningful improvement in downstream demand. For chrome ore producers, the message is clear: until China’s stockpiles start turning into consumption, the road to a price recovery remains uphill.
For more on the outlook for Chrome; see our Chrome forecasts.
Compiler: Khomotso Rabutla (khomotso@afriforesight.com)