

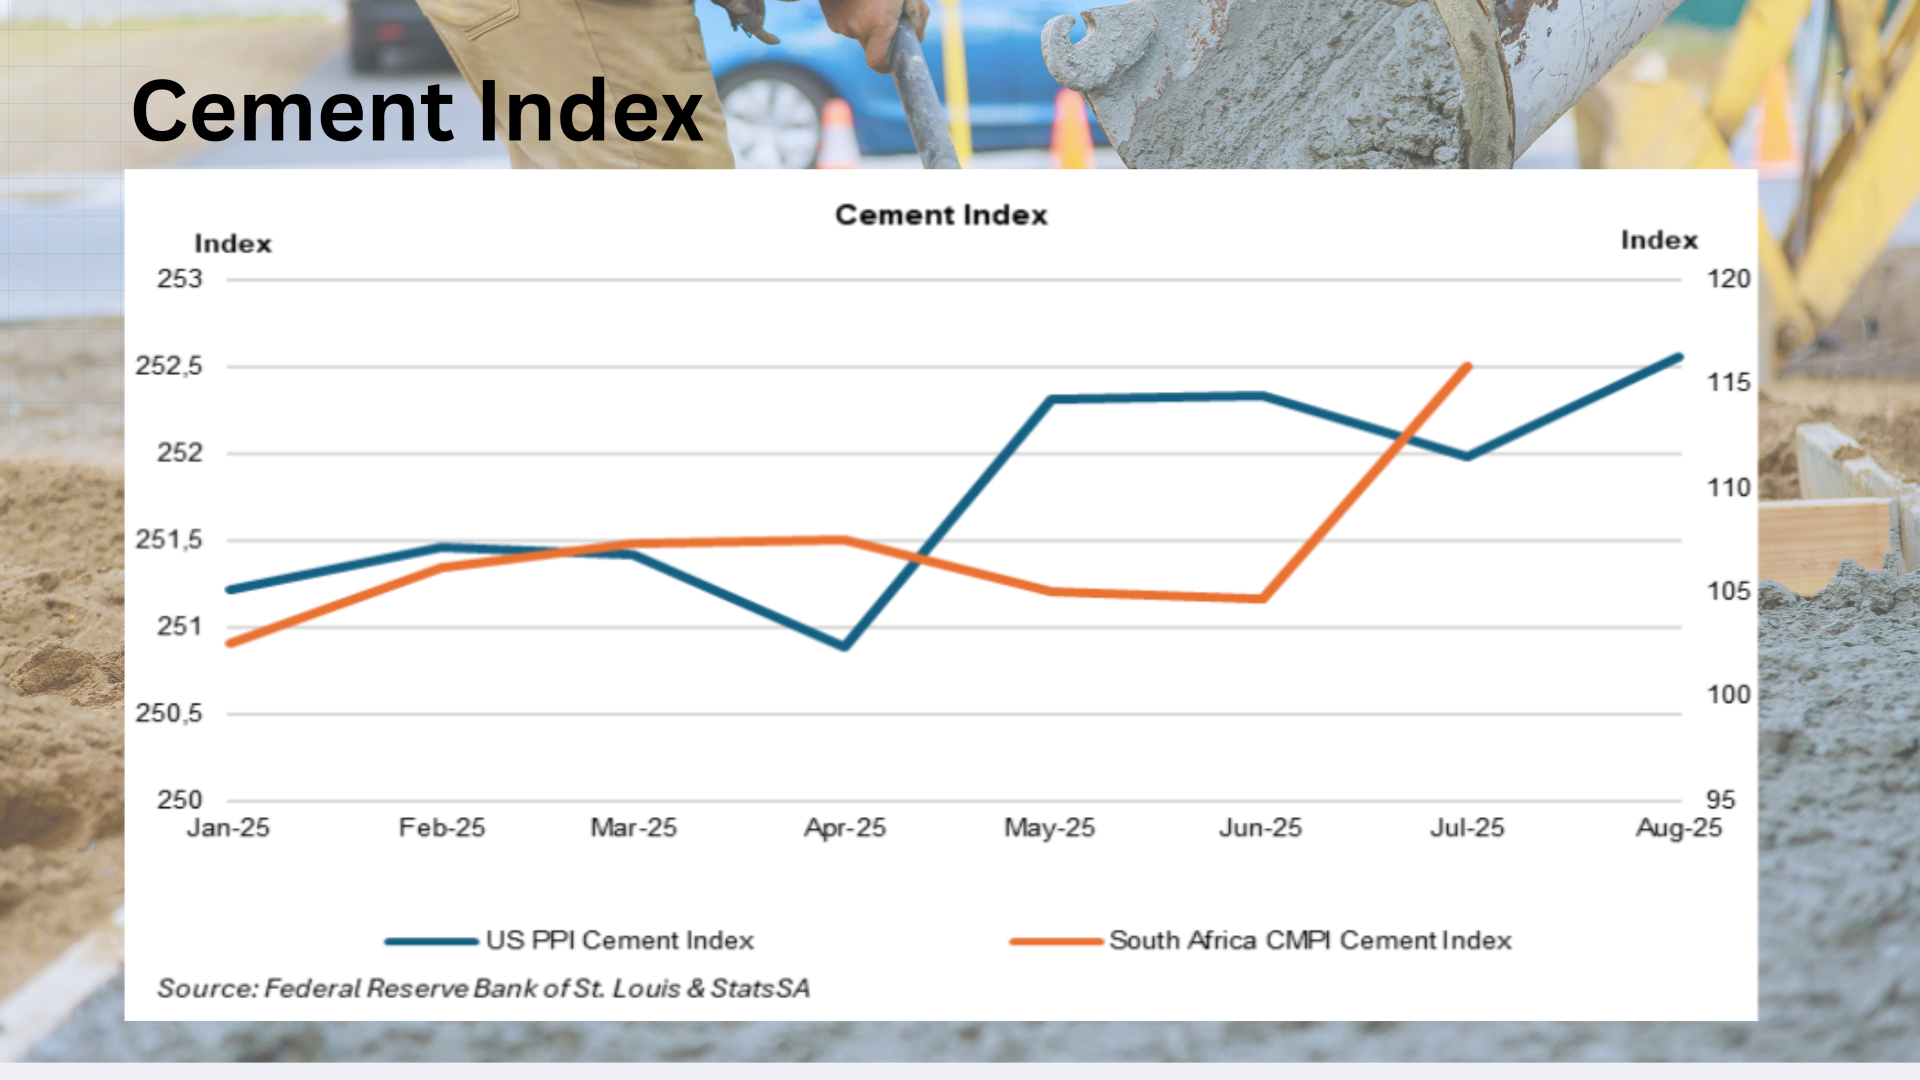
International cement prices (proxied by the US PPI series) have been trending upwards over 2025 amid the impact of US import tariffs and higher input costs, boosted by costly environmental regulations and efforts to reduce carbon emissions. South African prices moved sharply higher from June amid input material and electricity cost increases.
Rising prices have come despite weak international demand, as economic uncertainty slowed construction investment in general, exacerbated by the ongoing property sector slump and sharp slowdown in infrastructure investment growth in China; the US construction industry also faces greater headwinds.
Instead, tightening supply seems to be the main driver, as China (the world’s largest producer) continues to cut back capacity (started in earnest in 2022) amid slowing domestic demand and anti-pollution measures; however, Indian and African production is on the rise, with, for example, Dangote opening a new 3mtpa plant in Ivory Coast in October.
South African demand too has been struggling as the construction sector battles a slowdown, but faces a better outlook as government-led construction projects across various sectors and renewed investment in renewable energy capacity gains traction. Interest rate cuts over the past year can also provide new impetus to housing construction.
South African suppliers will hope to secure more of this new business, with production across the board running below designed capacity in recent years amid increased pressure from cheaper imports – cement imports increased 21.3% to 1.1mnt in 2024 from 2023 (mostly from Vietnam – graph), with a decrease of 5.8% to 631kt over the 1st half of 2025, from 2nd half 2024, amid weaker demand. Local suppliers have also requested tariff protection against cheap cement products, especially from Vietnam and China.

At Afriforesight, we help you stay ahead with award-winning, data-driven forecasts — not just on price, but on policy risks, sector demand, and strategic trade shifts.
For insights built for decision-makers, contact us at info@afriforesight.com / Follow us on LinkedIn