

LME nickel prices have retreated sharply from recent highs and remains subdued around the $16000–17000/t range – see graph below. While Indonesia’s decision to tighten 2026 nickel ore quotas initially provides an important floor for prices, further RKAB license approvals and potential quota increases are raising expectations that additional Indonesian ore will become available to domestic smelters during the 2nd half of the year.
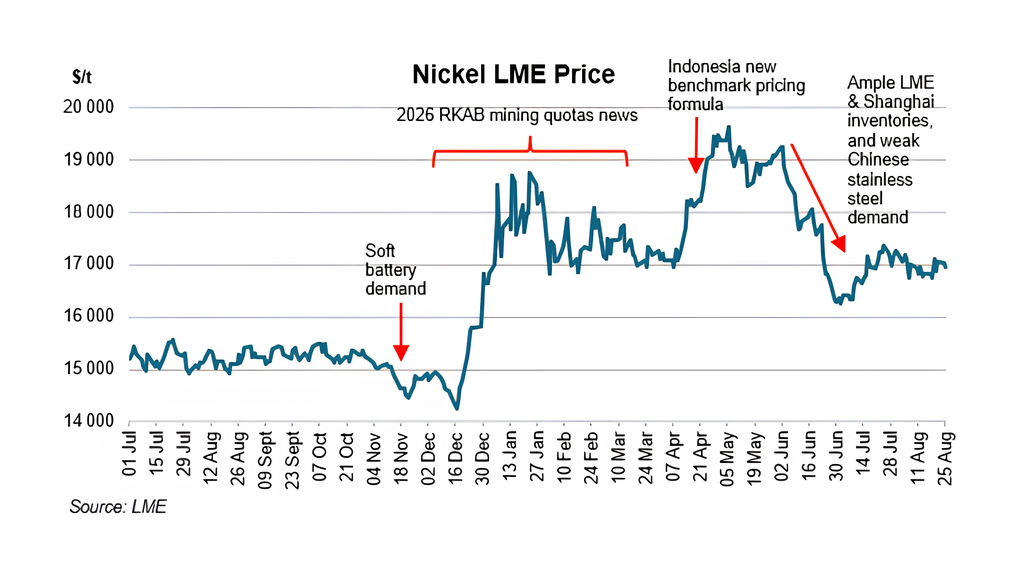
The latest quota developments have weakened the bullish supply narrative that supported nickel during the 1st half of 2026 and market sentiment remains cautious as miners assess how much additional ore will ultimately reach smelters. Indonesia’s decision to delay the planned windfall tax also removes one potential near-term constraint on the mining sector
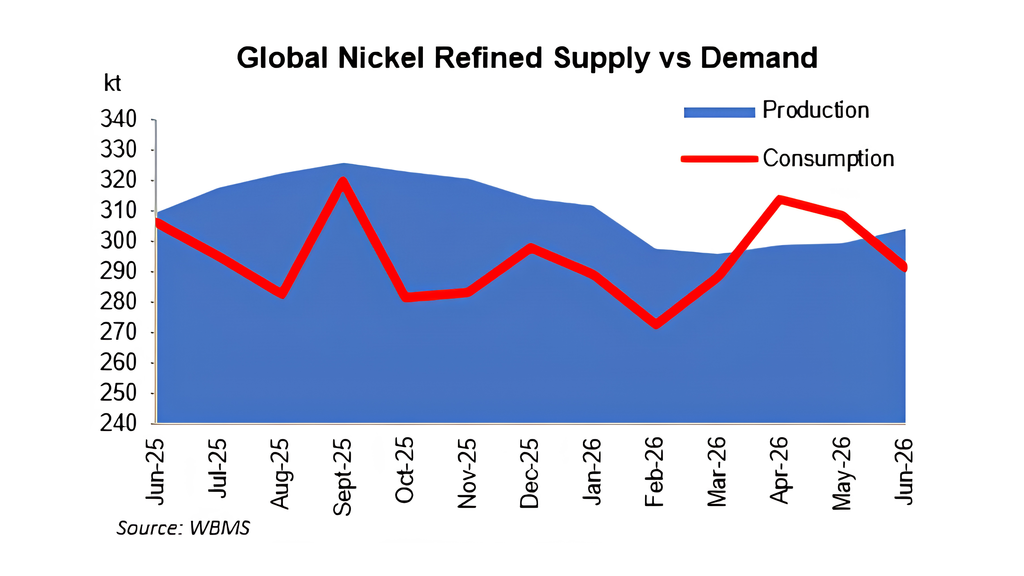
At the same time, the global refined nickel continues to show signs of ample supply. Global nickel consumption growth remains below earlier expectations, while stainless steel demand has yet to show a convincing recovery as China’s economy slows.
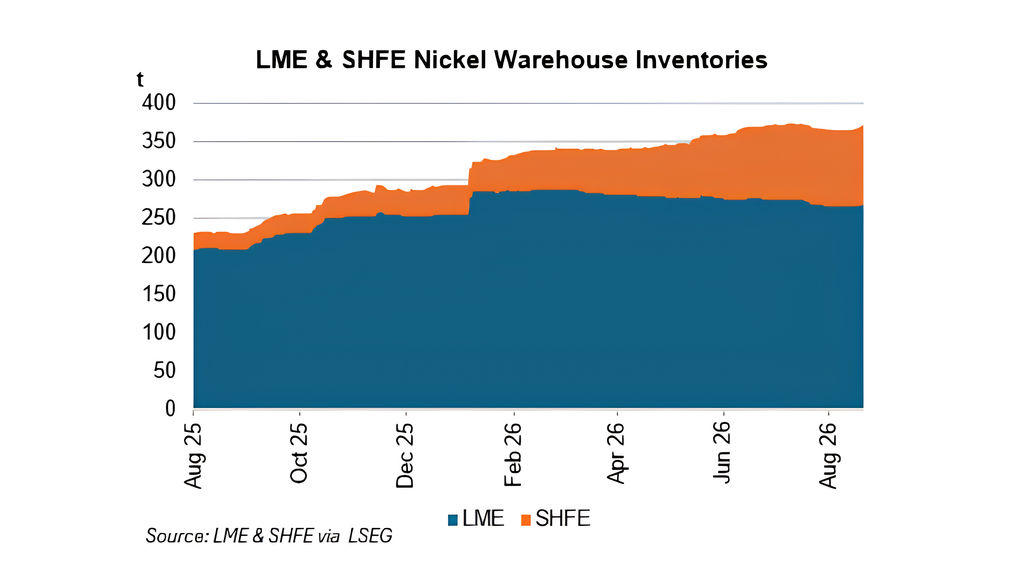
Rising inventories are an additional headwind for LME nickel prices. Despite periodic supply-side disruptions and Indonesian policy support, elevated exchange inventories indicate that the underlying refined nickel surplus has not been eliminated.
Indonesia’s mining policy will remain the main source of upside volatility, but the broader market fundamentals continue to point toward a well-supplied nickel market and limited upside for prices. Therefore, unless Indonesian quota management becomes significantly tighter again, the combination of ample production, declining consumption growth and rising inventories is likely to keep LME nickel prices subdued.
For more on the outlook for Nickel; see our Nickel forecasts.
Compiler: Khomotso Rabutla (khomotso@afriforesight.com)