

With gold prices bursting past $5 000/oz in early 2026 and maintaining levels comfortably above $4 000/oz since, South Africa’s gold sector continues to demonstrate resilience, with a strong performance by tailings retreatment operations and high‑grade underground mines providing the backbone of near‑term growth, even as the industry navigates structural challenges.
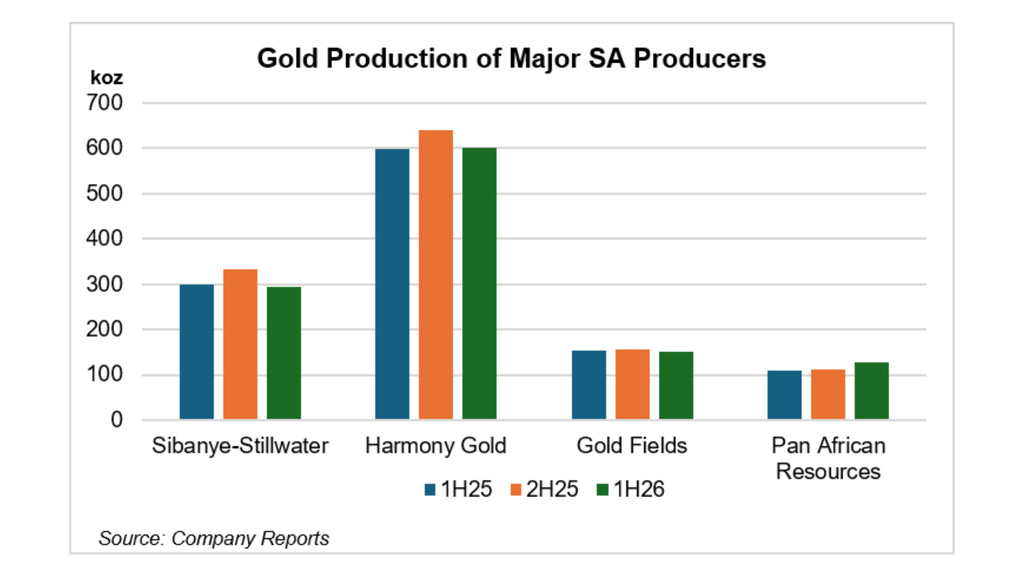
The majority of SA gold output stems from major producers Harmony Gold, Sibanye-Stillwater and Goldfields (see graph), which account for around 70% of the country’s total production. Over the last few years, however, growth in production has been led by smaller operators like Pan African Resources, who has built up a portfolio of projects, both in underground mines and tailing projects.
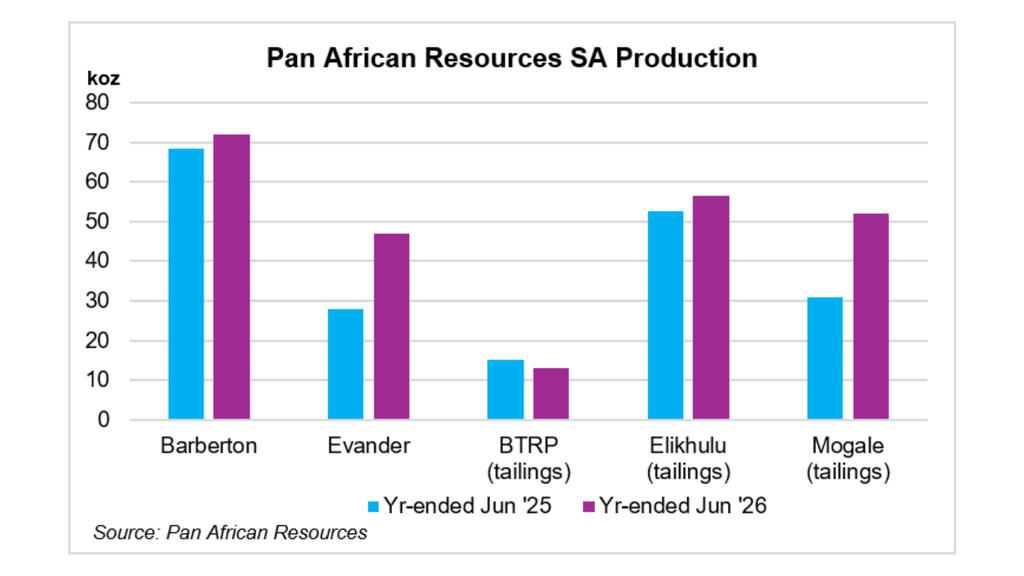
Indeed, Pan African’s tailings retreatment operations have been the standout contributors to a 23% increase in output to 240koz in the year ended June 2026 (see graph): Elikhulu produced 56koz at $1 231/oz AISC, while the newly expanded Mogale Tailings Retreatment added 51.9koz at $1 389/oz AISC. Its underground mines also delivered solid results: Barberton output rose to 72koz, supported by high‑grade ore from the Main Reef Complex and Rossiter orebodies, while Evander’s output surged 68% to 46.8koz on grades above 11g/t. Together, these operations underscore the company’s ability to balance cost‑efficient surface retreatment with high‑grade underground output.
Looking ahead, Pan African is advancing a pipeline of projects that will underpin long‑term growth:
- The Royal Sheba development at Barberton is targeting near‑surface ore, expected to add 40kozpa from 2027, processed through the Barberton Tailings Retreatment Plant.
- The Soweto Cluster tailings retreatment project has completed its definitive feasibility study, outlining 35-40kozpa expected over 15 years, with an investment decision due by year‑end.
- The Poplar project adds further depth to Pan African’s growth portfolio, ensuring production stability beyond the current cycle.
Not all growth has stemmed from tailing operations, with West Wits Mining’s Qala Shallows, the first new underground mine in South Africa in 15 years, producing its first gold in March 2026 and is ramping up toward 70kozpa for 12 years. Beyond Pan African and West Wits, the broader South African gold industry is also investing in future supply:
- Sibanye‑Stillwater has overcome its concerns about regulatory uncertainty to approve the Burnstone project, targeting 130kozpa over a 25‑year mine life, with steady‑state output expected post‑2029.
- Harmony Gold continues to advance extensions at Moab Khotsong, Mponeng, Tshepong North, and Doornkop.
- Theta Gold Mines has confirmed 1mnoz over 13 years in its revised feasibility study, with commissioning planned for late‑2026 and first gold pour in early‑2027.
All told, South African gold output is being sustained by strong near‑term performance from tailings retreatment and high‑grade underground mines, while new projects promise to extend mine life and stabilize production over the long term.
For more on the outlook for Gold; see our Gold forecasts.
Compiler: Dina Alleluya (dina@afriforesight.com)