

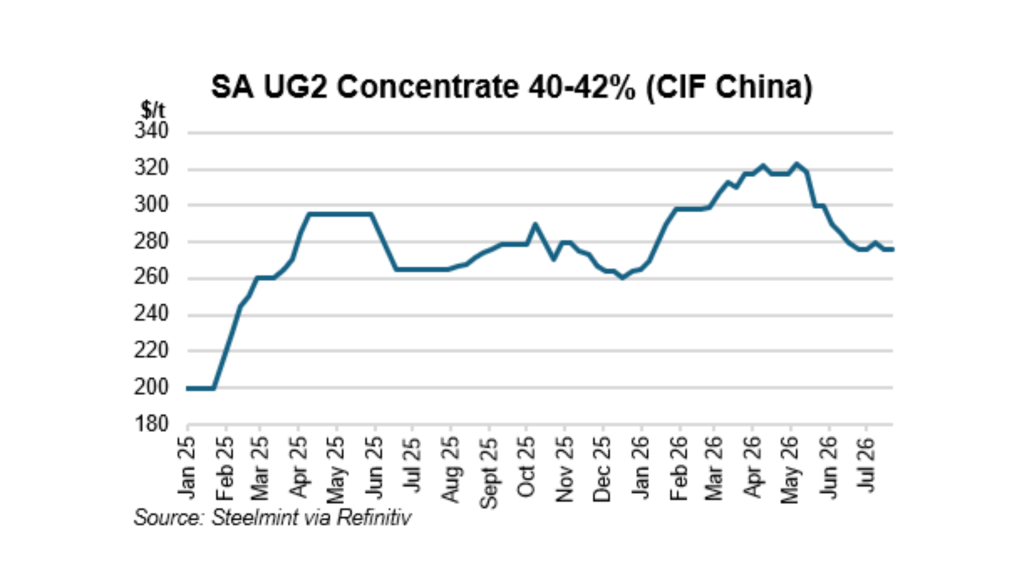
Chrome ore prices climbed steadily over the first few months of 2026 to a near decade-high in mid-May on the back of various supply disruptions – mostly weather-related – but have fallen back sharply since (see graph), even as China’s import demand remains healthy, but continued strong shipments from South Africa, Zimbabwe and Turkey, coupled with seasonally weaker stainless steel production boost Chinese port inventories.
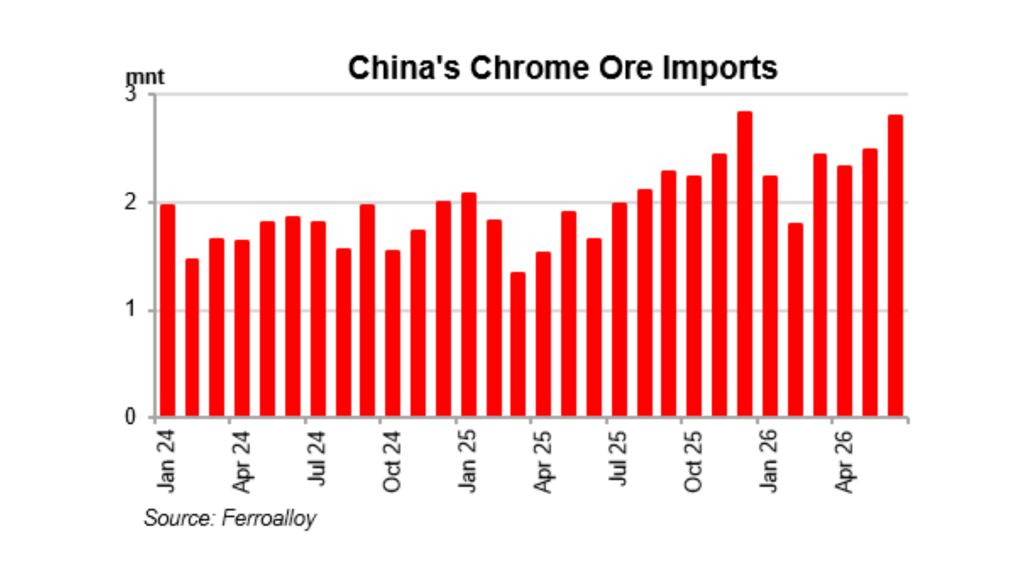
China’s chrome ore imports continued to increase during the first half of 2026; however, stronger imports have coincided with a significant build-up in Chinese port inventories as stainless steel production entered its seasonal slowdown, leaving buyers well covered. South African chrome ore account for the majority of arrivals, with Zimbabwe and Turkey the other major suppliers.
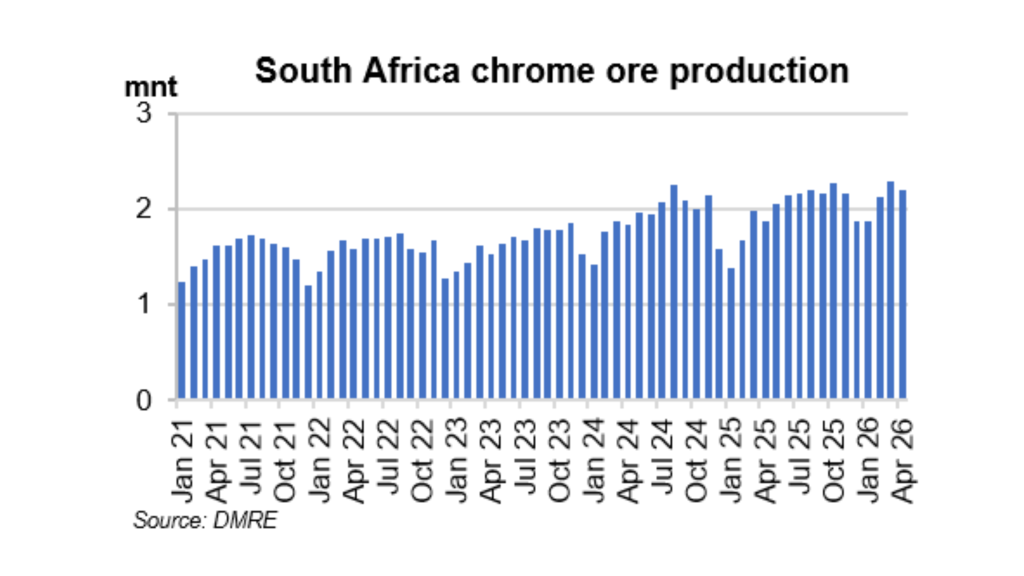
South Africa’s chrome ore production has remained resilient in 2026 (see graph), reinforcing the country’s position as China’s largest chrome ore supplier. Export-focused producers continued to deliver strong volumes, with Glencore reporting stable chrome ore production during the period as their domestic ferrochrome smelting remained largely suspended for much of the reporting period. Tharisa also maintained strong operational momentum, producing 394kt of chrome concentrates during the 2nd quarter of 2026 and remains on track to achieve its annual production guidance of 1.50 – 1.65mnt. Chrome production from PGM operations, including Northam and Anglo American Platinum, also continued to provide additional export volumes.
Outside South Africa, Zimbabwe continues to expand chrome ore production and beneficiation capacity in an effort to increase domestic value addition, However, limited smelting capacity means a substantial share of its chrome ore production continues to be exported to China however, limited smelting capacity means a substantial share of its chrome ore production continues to be exported to China. Turkey remains a reliable supplier of high-grade chrome ore into China , with shipments from all three origins contributing to ample ore availability and elevated Chinese port inventories.
Chrome ore prices are expected to remain under pressure in the near term, with a sustained price recovery likely dependent on a meaningful recovery in Chinese stainless steel production and a consequent reduction in Chinese inventories.
For more on the outlook for Chrome; see our Chrome forecasts.
Compiler: Khomotso Rabutla (khomotso@afriforesight.com)